Selling your business without a broker is possible, but it demands careful planning and attention to detail. We at Unbroker know that many owners want to handle the sale themselves to save on commissions.
This guide walks you through the DIY business sale steps you need to follow, from preparing your business to closing the deal. You’ll learn what works and where most sellers stumble.
Getting Your Business Ready to Sell
Selling your business without professional help requires solid financial documentation and an honest assessment of what it’s worth. Most DIY sellers fail at this stage because they underestimate how much time preparation takes. The IRS requires business tax returns for the past three years, so gather those first along with profit and loss statements, balance sheets, and bank statements. Buyers will request these documents within days of showing serious interest, and if you scramble to find them, you’ll lose credibility. According to data from BizBuySell, businesses with complete financial records typically sell faster than those without organized documentation.
Organize Your Financial Records
Start by exporting everything dating back three years from your accounting software right now. If you use QuickBooks, generate your standard financial reports and save them as PDFs. For scattered records across spreadsheets and emails, consolidate them into one organized folder before marketing begins. This single step prevents delays when serious buyers appear.
Value Your Business Accurately
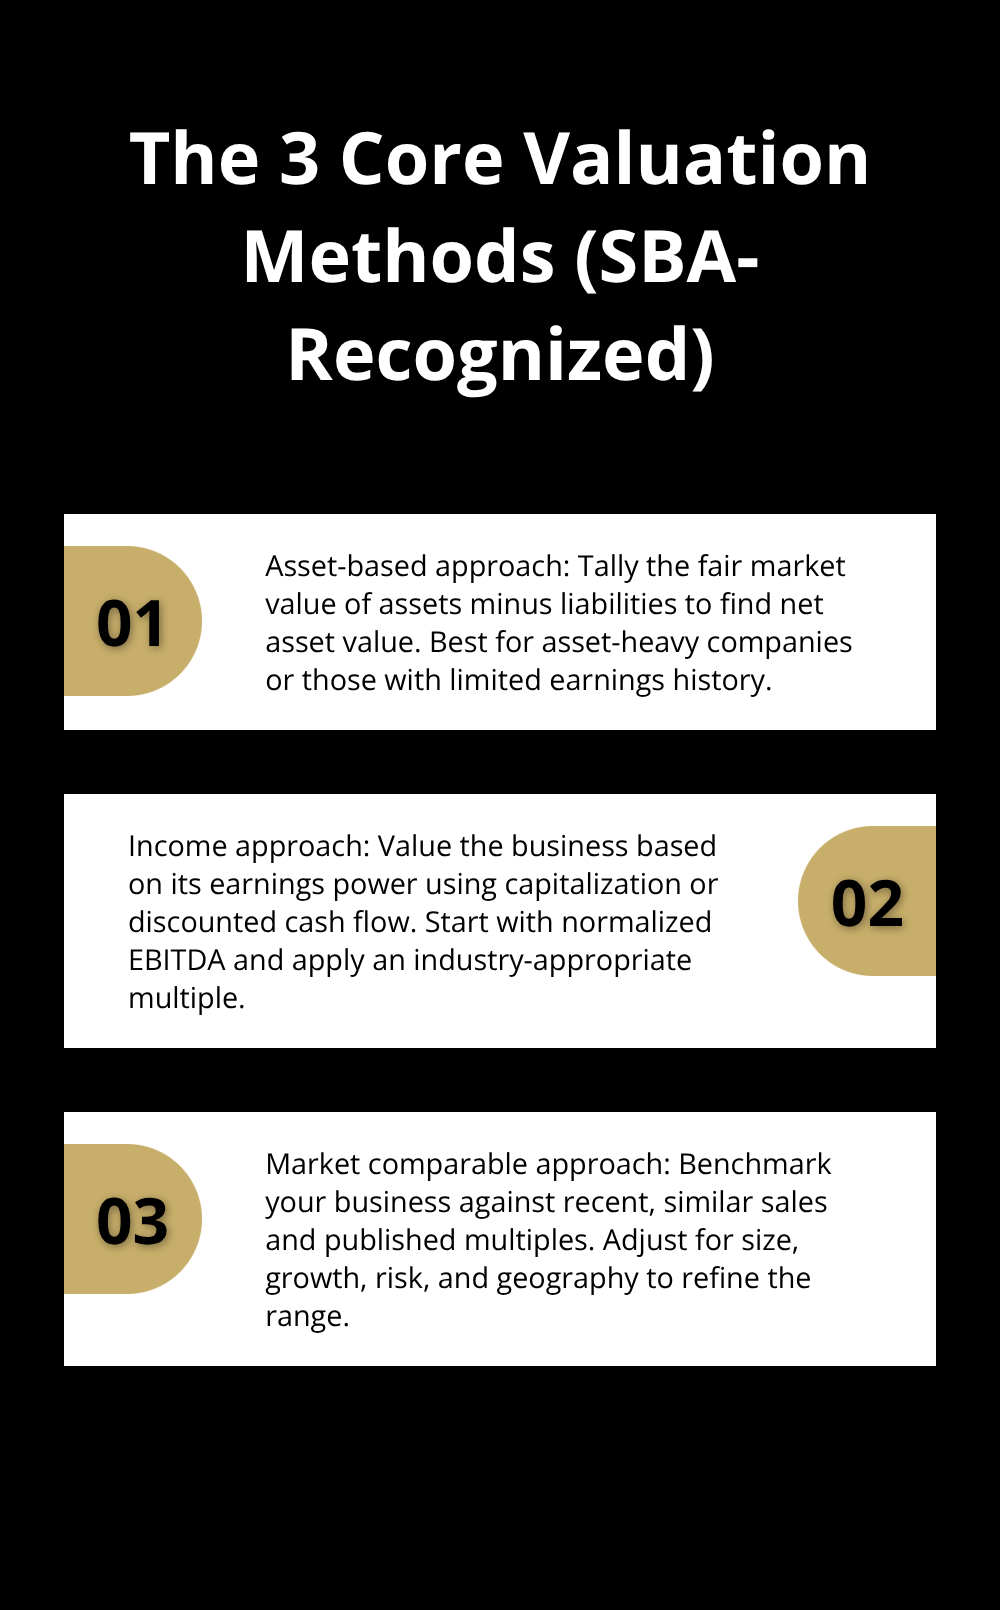
Overpricing kills deals immediately, so price based on what the market actually pays, not on gut feeling or what you think you deserve. The SBA suggests using three valuation methods: the asset-based approach, the income approach, and the market comparable approach. Start with the income approach by calculating your EBITDA (earnings before interest, taxes, depreciation, and amortization) over the past three years and multiply by an industry multiple. Manufacturing businesses typically sell for 4-6x EBITDA, while service businesses range from 2-3x EBITDA. If your business generated $200,000 in EBITDA and operates in services, expect a realistic valuation between $400,000 and $600,000.
Compare this against similar businesses that sold recently in your area by checking business sale databases or local business brokers’ sold listings. Try pricing your listing 10-15% above your target to leave room for negotiation, but don’t inflate it beyond market reality.
Fix Operational Problems Before Listing
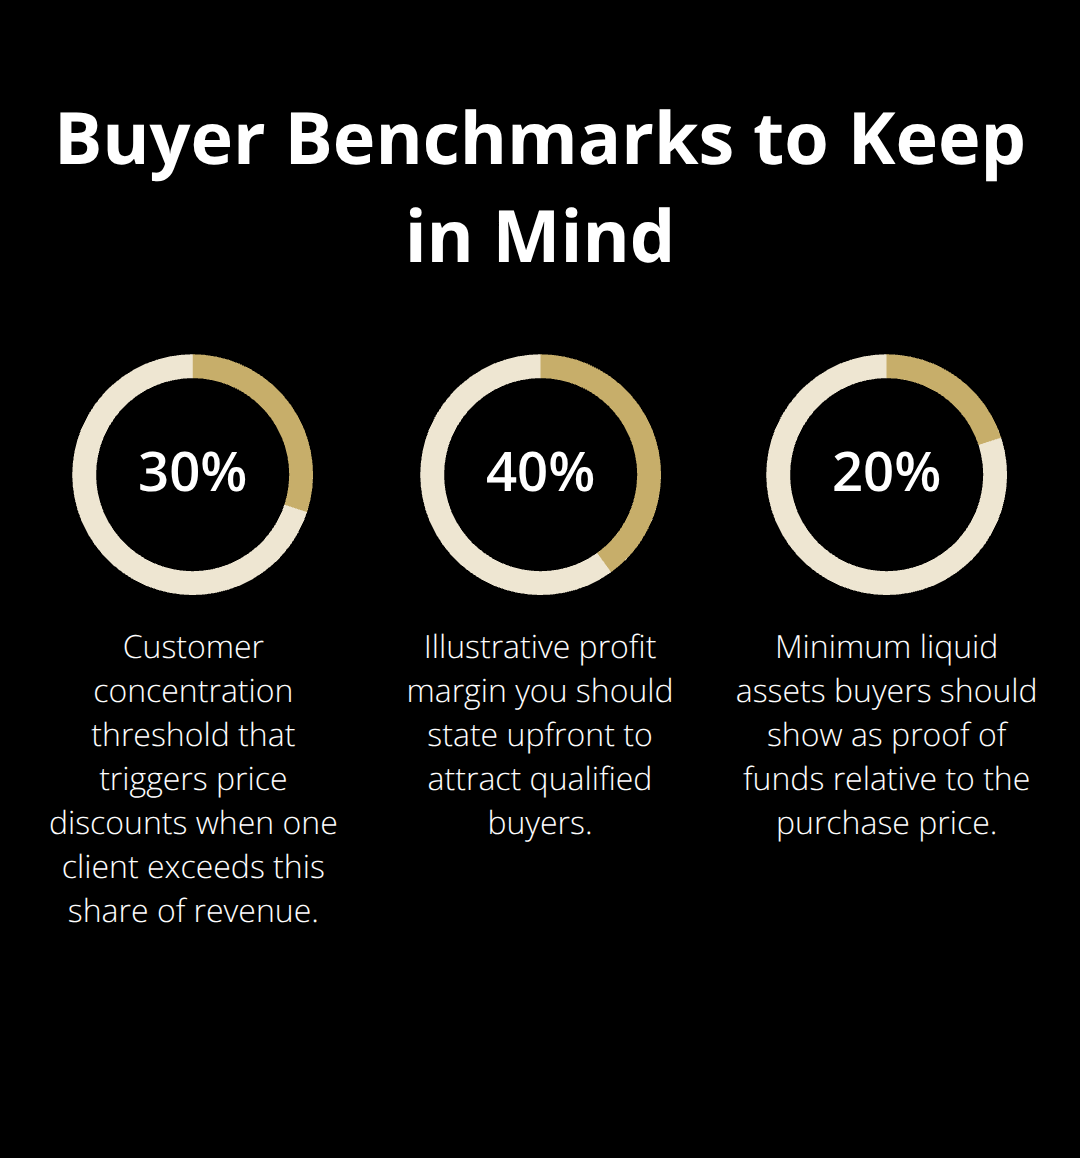
Operational problems become deal-killers during buyer due diligence, so fix them now. Review your customer concentration: if one customer represents more than 30% of revenue, buyers will heavily discount your price because the business depends on that relationship. Reach out to your largest customers and discuss long-term commitments or contracts that survive the sale. If a key employee handles critical operations, document their responsibilities and create a transition plan showing they’ll stay post-sale. Buyers want stability, not surprises.
Address any outstanding compliance issues like unpaid taxes, licensing violations, or pending lawsuits. Contact your local business licensing agency and verify everything is current. If you’ve been operating without proper permits, get them now rather than having a buyer’s attorney discover this during due diligence.
Review Contracts for Transfer Restrictions
Audit your contracts for change-of-control clauses that might trigger termination when ownership transfers. Supplier agreements, lease agreements, and service contracts sometimes require approval from the other party before a new owner takes over. Reach out to critical vendors and landlords now to understand their transfer policies. Getting these details sorted before listing prevents buyers from walking away during negotiations and positions you to move forward with confidence when serious interest arrives.
Marketing and Finding Buyers Without Professional Help
Your listing is the only tool most DIY sellers have to attract buyers, so it needs to work harder than a standard classified ad. Most DIY sellers underestimate how specific and detailed their listing must be to stand out. Write a description that answers the questions buyers actually ask: What does this business do? How much revenue does it generate? What are the profit margins? Who are the customers? What equipment or inventory comes with the sale? Include concrete numbers like annual revenue, customer count, repeat customer percentage, and years in operation. If your business generated $500,000 in annual revenue with 40% margins, state that upfront. Vague listings attract tire-kickers and waste your time fielding useless inquiries.
Create a Compelling Business Listing
Post your listing on multiple platforms simultaneously rather than testing one site first. Online business marketplaces, local classified sites, industry-specific forums, and LinkedIn all reach different buyer segments. The more exposure your listing gets, the higher your odds of finding a serious buyer willing to pay fair market value. Avoid using your personal email or phone number in listings; create a separate email address specifically for buyer inquiries so you can filter spam and maintain boundaries. A professional presentation signals that you take the sale seriously and attracts qualified prospects.
Leverage Online Platforms and Networks
Screening inquiries ruthlessly saves weeks of wasted time with unqualified buyers. When someone responds to your listing, ask them three qualifying questions immediately: Do you have liquid capital available to fund this purchase, or will you need financing? What’s your timeline for closing? Have you purchased a business before? A qualified buyer should supply a personal financial statement, a recent credit score, and a summary of relevant business or industry experience. Require a confidentiality agreement before sharing detailed financial information with any prospect. This simple document protects your business information and prevents competitors from learning your numbers.
Handle Initial Buyer Inquiries and Screening
Schedule phone calls with qualified prospects before allowing them to visit your business in person. A fifteen-minute call filters out window shoppers and people who misunderstood what your business actually does. During the call, listen more than you talk. Ask prospects what they’re looking for in an acquisition and whether your business fits their criteria. If they seem genuinely interested and qualified, invite them to visit and review documentation. Track every inquiry in a spreadsheet noting contact date, their questions, your responses, and follow-up dates. This prevents you from losing track of promising leads or accidentally ghosting someone who might become your buyer.
Once you’ve identified serious prospects and scheduled visits, the next phase involves structuring offers and managing the legal complexities that arise when buyers conduct their investigation.
Negotiating the Deal and Managing Legal Requirements
Serious buyers will submit an offer once they’ve reviewed your business, and this is where most DIY sellers make costly mistakes. Your first offer rarely reflects what a buyer will ultimately pay, so treat it as a starting point for negotiation rather than a final number. When an offer arrives, resist the urge to accept immediately even if it matches your asking price. Request a written offer that specifies the purchase price, the breakdown between asset sale versus stock sale, the proposed closing date, what inventory or equipment transfers with the business, and any seller financing the buyer expects. A vague verbal offer creates confusion and conflict later.
Verify Buyer Qualifications and Proof of Funds
Ask the buyer for proof of funds demonstrating they can actually close the deal. This single requirement eliminates tire-kickers who lack capital and saves weeks of wasted negotiation with unqualified prospects. Request a personal financial statement and recent bank statements from the buyer showing liquid assets equal to at least 20% of the purchase price. If the buyer hesitates to provide proof of funds, they’re not serious.
Structure Offer Terms and Price Negotiations
Price negotiations typically involve multiple counteroffers before reaching agreement. Start by calculating your walk-away price-the absolute minimum you’ll accept-and communicate your initial counteroffer within two business days of receiving their proposal. Slow responses signal disinterest and weaken your negotiating position. When countering, adjust the price in smaller increments as negotiations progress rather than making large jumps that signal desperation. If the buyer offers $400,000 and your asking price was $500,000, don’t immediately drop to $450,000; counter at $480,000 and explain your reasoning based on the financial performance and market comparables you researched earlier.
The terms matter as much as price. Negotiate the earnout period (how long you remain available post-sale to assist transition), seller financing terms if applicable, and what happens if the buyer discovers undisclosed problems after closing. Many DIY sellers accept lower prices to avoid seller financing, which is smart because collecting payments from a new owner creates ongoing liability. Push for all-cash deals or require the buyer to secure bank financing before closing.
Navigate Legal Documents and Contracts
Once you’ve agreed on price and basic terms, you enter the legal phase where most DIY sellers face real trouble. You need a business purchase agreement protecting you from liability claims after the sale closes. This document should specify what assets transfer, what liabilities the buyer assumes, representations and warranties you’re making about the business condition, indemnification provisions protecting you from hidden problems discovered later, and contingencies like financing approval or third-party consent requirements.
Do not use a generic template from a free website; these documents miss industry-specific issues and leave you exposed. Hire a business attorney for 2-4 hours to review and customize a template specific to your business type and the sale structure. This costs $500 to $1,500 but prevents six-figure liability exposure later.
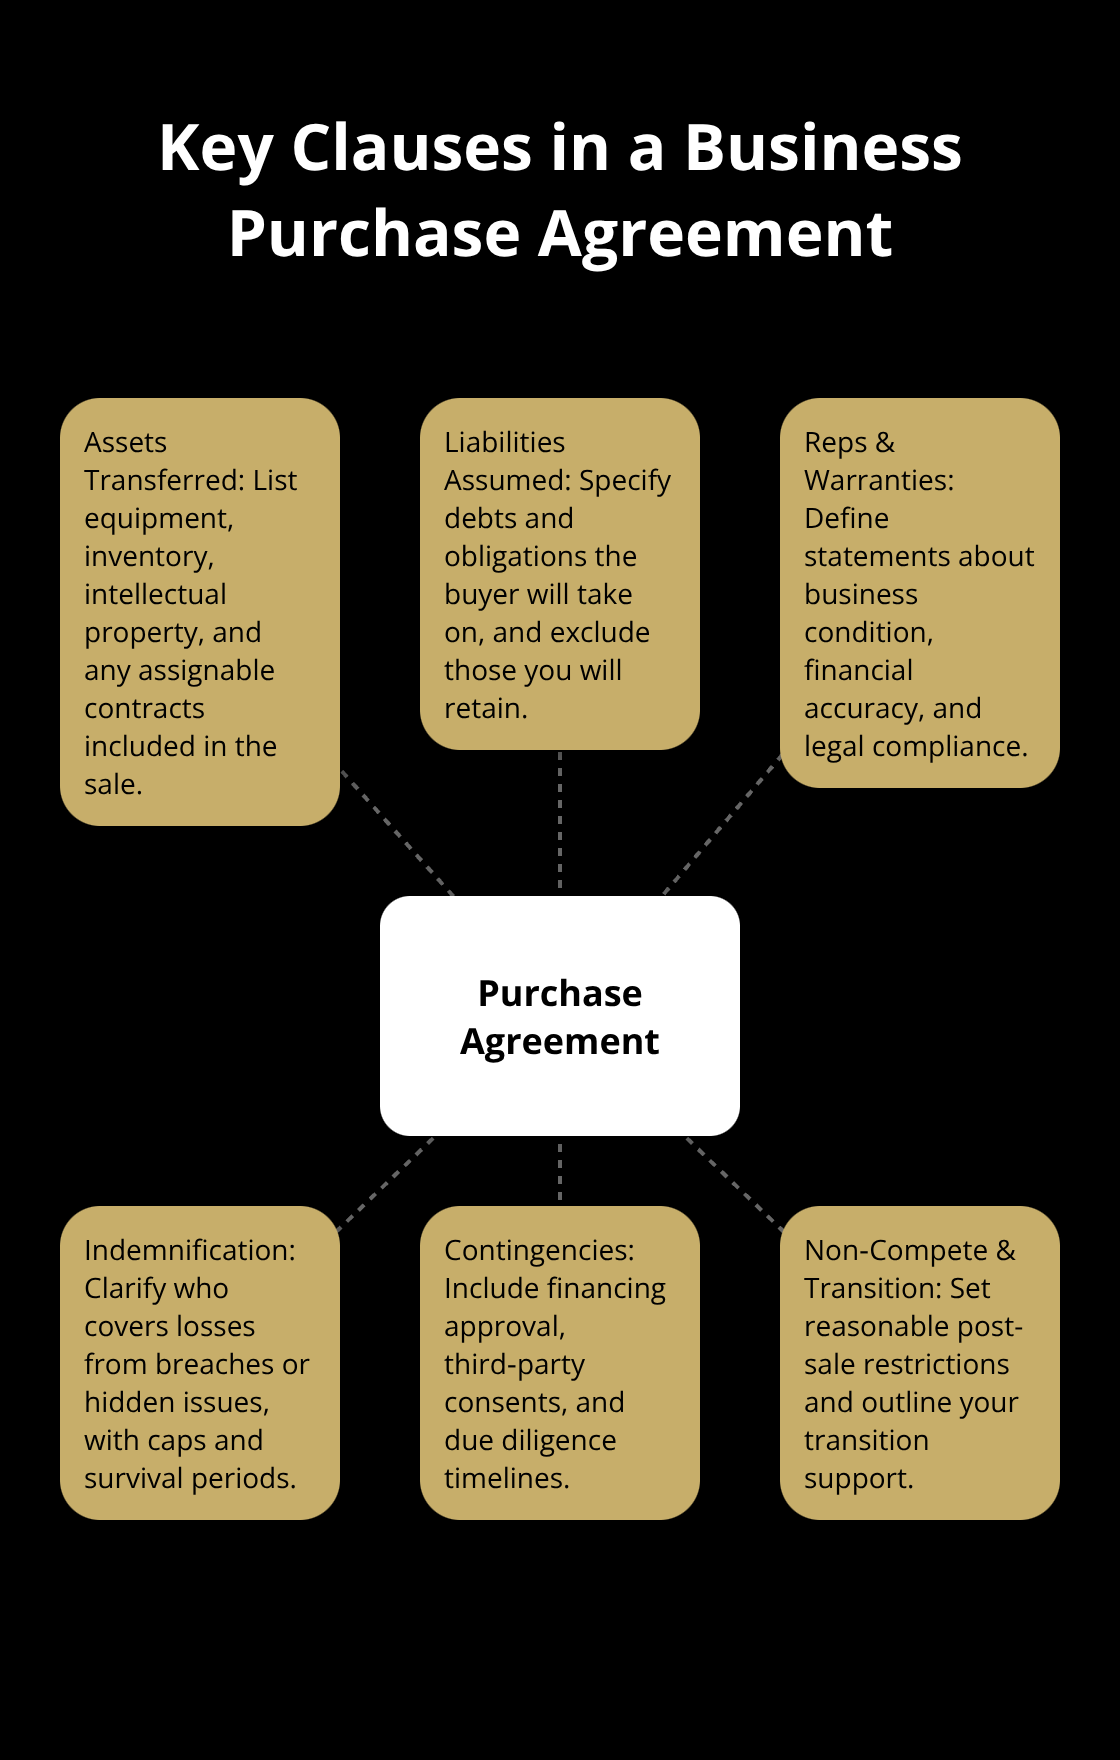
The attorney will flag clauses that could create personal liability, verify compliance with state business sale laws, and confirm that restrictive covenants preventing you from competing after sale are reasonable and enforceable. Request that the buyer’s attorney draft the initial agreement; reviewing their draft costs less than starting from scratch, and their lawyer is unlikely to include provisions that harm you since both parties benefit from balanced terms.
Handle Due Diligence Without Professional Guidance
Due diligence is where buyers investigate everything about your business, and this is your last opportunity to control the narrative before closing. The buyer will request due diligence documentation including customer lists, contracts, employee records, tax returns, insurance policies, litigation history, and environmental compliance reports. Organize these documents in a secure digital folder accessible only to qualified buyers who’ve signed confidentiality agreements. Prepare a summary document explaining any items that might raise red flags-previous lawsuits resolved, customer concentration you’ve already addressed through contracts, or operational changes you’ve made. Transparency prevents surprises during final negotiations.
If the buyer discovers a major issue you concealed, they’ll either demand a price reduction or walk away entirely. Respond to all due diligence requests within five business days; slow responses frustrate buyers and signal disorganization. Some buyers will hire accountants or industry consultants to validate your financial claims and operational performance. Cooperate fully with these third-party reviews and answer questions directly rather than deflecting. If your numbers don’t withstand scrutiny, the buyer will reduce their offer or terminate the deal. The goal is closing quickly with minimal friction, which happens when you provide complete, accurate information upfront.
Wrapping Up Your DIY Business Sale
Selling your business without a broker saves commission costs, but the hidden expenses add up fast. Most DIY sellers underestimate the time required for financial preparation, buyer screening, legal document review, and due diligence management-you’ll spend 100+ hours on tasks a broker handles routinely, and mistakes during negotiation or contract drafting can cost tens of thousands in lost value or post-sale liability. The biggest pitfall is pricing incorrectly, as overpriced listings sit unsold while underpriced ones leave money on the table permanently.
DIY business sale steps work only if you commit to doing them thoroughly and honestly. Legal mistakes create the most damage-missing change-of-control clauses, failing to structure indemnification properly, or accepting vague offer terms leads to disputes after closing that drain your time and money. Many DIY sellers also fail to separate personal and business finances adequately, making valuation and buyer confidence nearly impossible.
Professional help becomes necessary when you lack legal expertise, face complex tax situations, or need access to qualified buyer networks beyond your personal connections. We at Unbroker built our platform specifically for sellers who want expert support without traditional broker overhead, offering AI-driven buyer matching with expert advisors, premium marketing through syndication partners, legal document templates, and negotiation assistance-all with a 6% success fee paid only when your business sells.